
IRS code 810 on your transcript: what a refund freeze means and when code 811 lifts it
Short answer
IRS code 810 on a transcript is a refund freeze: it stops the IRS from issuing a refund, applying an offset or moving the overpayment to next year until a TC 811 reverses it. IRS compliance or return integrity staff place it. For the most common preventative freezes, the Internal Revenue Manual tells assistors to have filers allow 180 days from the TC 810 date unless a letter arrives first. The refund is scheduled only when TC 846 posts.
- 01TC 810 meaning
- Refund freeze: no refund, offset or credit elect (Document 6209)
- 02Release code
- TC 811, in whole or in part
- 03Who places it
- IRS Compliance or Return Integrity and Compliance Services (RICS)
- 04Typical wait (RC 6 and RC 7)
- Allow 180 days from the TC 810 date (IRM 21.5.6.4.10)
- 05After you answer a letter
- Allow 60 days, then a referral and 90 more days
- 06Refund scheduled
- Only when TC 846 posts
What does IRS code 810 mean on a transcript?
IRS code 810 is the transaction code for a refund freeze. IRS Document 6209 says a TC 810 freezes the tax year from refunds, offsets and credit elect, which is the choice to apply an overpayment to next year's estimated tax. While the freeze is open, no refund can leave the account for that year, even if every other line looks clean.
The line does not add tax or remove credits. It only stops money from going out. The Internal Revenue Manual (IRM 21.5.6.4.10) calls the result an -E freeze on individual accounts and says TC 810 is placed by Compliance or by Return Integrity and Compliance Services (RICS), the IRS unit that screens returns for identity theft and false refund claims.
Why does the IRS put a refund freeze on an account?
Each TC 810 carries a responsibility code (RC) that records which program set it. The IRS manual tells phone assistors to look up that code in IDRS, the IRS's internal account system, so expect to learn the reason from a letter or a call rather than from the transcript line. IRM 21.5.6.4.10 lists these codes for individual accounts:
| Code | Program that set the freeze | What the IRS manual says |
|---|---|---|
| RC 1 | Pre-filing notification | Handled as a compliance refund hold project |
| RC 2 | Abusive Tax Shelter Detection Team (ATSDT) | Handled as a compliance refund hold project |
| RC 3 | Credit holds on EITC, ACTC, Premium Tax Credit or American Opportunity Tax Credit claims | Appears with Examination code TC 424 or, for some credits, a TC 971 AC 128 |
| RC 4 | Return Integrity Verification Operations (RIVO) screen for frivolous returns | If the return is judged frivolous, Letter 3176C follows; reply within 30 days |
| RC 6 | Entity fabrication or suspicious income document review | Allow 180 days from the TC 810 date |
| RC 7 | RICS preventative refund freeze | Allow 180 days from the TC 810 date |
Codes 4, 6 and 7 are preventative screens: the IRS has not decided anything is wrong, but it wants to confirm the income, withholding or credits before money goes out. Code 3 is tied to a review of a refundable credit claim, often by Examination.
How long does a code 810 refund freeze last?
No law sets a deadline for releasing a TC 810. For the preventative freezes most filers meet, responsibility codes 6 and 7, IRM 21.5.6.4.10.2 and 21.5.6.4.10.3 tell assistors to advise allowing 180 days from the date of the TC 810. If 180 days pass with no letter, the assistor sends a referral to RIVO and tells the caller to allow 90 more days.
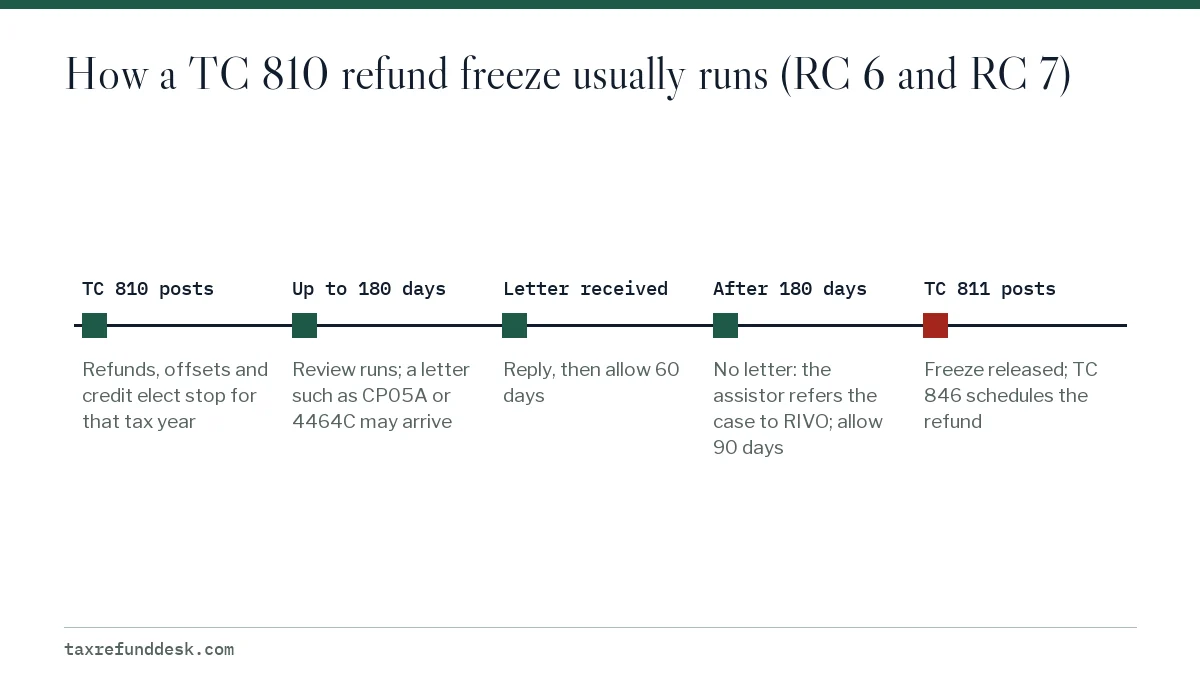
A letter moves the clock to your reply. The manual names CP05A, Letter 105C, Letter 3219C, Letter 4464C and Letter 4800C as notices that can come with these freezes. After you respond, it says to allow 60 days; if nothing changes by then, the assistor can refer the case and you allow another 90 days.
| Situation | What the IRS manual says to allow |
|---|---|
| RC 6 or RC 7, no letter yet | 180 days from the TC 810 date |
| A letter arrived and you have not replied | Reply, then allow 60 days |
| You replied and 60 days passed | Referral to RIVO, then 90 days |
| 180 days passed and no letter came | Referral to RIVO, then 90 days |
| Amended return adjusted, RC 6 or RC 7 still open | 45 days for the refund |
| RC 4 and Letter 3176C received | Reply and file a corrected return within 30 days |
What does code 811 mean after a code 810?
TC 811 reverses the refund freeze. Document 6209 says it can release the freeze in whole or in part. An 811 with a zero amount releases the 810 and all the credit on that tax year, as long as no other freeze is open. An 811 with an amount releases an equal amount of credit and leaves the rest held.
An 811 is not the refund. Look for TC 846, refund of overpayment, with a date after it; our page on code 846 explains how that date relates to the deposit. If the 811 posts and no 846 follows, another hold such as TC 570 may still be open, or an offset code such as TC 898 may show the money went to a debt.
Is code 810 the same as code 570?
No. Both stop a refund, but they set different freezes and are released by different codes.
| Point | TC 570 | TC 810 |
|---|---|---|
| Document 6209 title | Additional liability pending or credit hold | Refund freeze |
| Freeze it sets (IRM 21.5.6) | -R freeze | -E freeze on individual accounts |
| What it blocks | Refunds and offsets | Refunds, offsets and credit elect |
| Usual release | TC 571, or a TC 290 (often $0.00) | TC 811 |
The two can sit on the same tax year. When they do, both must be released before TC 846 can post, which is why a TC 571 alone does not always bring the refund.
What should you do if your transcript shows code 810?
- Note the date on the TC 810 line and count forward 180 days. That is when the IRS manual has assistors escalate a freeze that has no letter.
- Watch your mail and your IRS online account for CP05A, Letter 105C, 3219C, 4464C, 4800C or 3176C, and answer by the date printed on it.
- Send only what the letter asks for, keep copies, and record the date the IRS received your reply.
- If the letter shows a real mistake on your return, the IRS manual says assistors encourage filing an amended return; our Form 1040-X guide shows how.
- If the freeze outlasts these windows and the delay is causing financial hardship, see our hardship refund request page for when the Taxpayer Advocate Service can step in.
Calling before the waiting period ends rarely changes anything. The IRS manual says a phone assistor cannot resolve a TC 810; the unit that set it has to release it.
A long freeze can earn interest. The IRS generally pays interest when it issues a refund more than 45 days after the later of the due date or the date it received the return, as our page on interest on late refunds explains. For the other codes that appear beside an 810, see the IRS transcript codes overview.
Common questions
What does code 810 refund freeze mean?
It means the IRS has frozen that tax year so no refund, offset or credit to next year can go out. The freeze stays until a TC 811 posts, and the refund is scheduled only when a TC 846 follows.
How long does a TC 810 freeze last?
There is no fixed limit. For the common preventative freezes, responsibility codes 6 and 7, the IRS manual tells assistors to have callers allow 180 days from the TC 810 date, or 60 days after replying to a letter.
Does code 810 mean I am being audited?
Not necessarily. Responsibility code 3 ties the freeze to a credit review, often by Examination and shown with a code such as TC 424, while codes 4, 6 and 7 are preventative screens by the IRS return integrity units. An examination comes with its own letter.
Will calling the IRS release a code 810?
No. The IRS manual says phone assistors cannot resolve a TC 810. They can look up which unit set it and, once the waiting periods have passed, send a referral to that unit.
What if code 811 posted but no refund came?
Check for another open hold such as TC 570, an offset code such as TC 898, or a TC 846 with a date. Document 6209 says an 811 releases credit only when no other freeze is in effect.
Sources
- IRS Document 6209, Section 8A: Master File Codes irs.gov
- IRM 21.5.6, Freeze Codes irs.gov
- Taxpayer Advocate Service: held or stopped refunds taxpayeradvocate.irs.gov
We check figures against these official pages. Rules change; confirm anything that affects a deadline or payment with the agency before you act.
Tell us what happened
Describe your situation and our editors will use it to improve this guide. If you leave your email, we may reply with a pointer to the right page or official contact. We never share your details.