
IND-517-02 rejection code: your dependent filed their own return
Short answer
The IND-517-02 rejection code means a Social Security number you listed as a dependent is already the primary or spouse SSN on another return. Usually the dependent filed their own return without saying someone else can claim them. The IRS fixes are to file without that dependent, wait until their amended return is accepted, or mail your return on paper.
- 01What IND-517-02 checks
- Dependent SSN appears as a filer (primary or spouse) on another return
- 02Most likely cause
- The dependent filed their own return
- 03IRS fix options
- Remove the dependent, wait for their amended return, or mail a paper return
- 04Sister code
- IND-507-01 (SSN already claimed as a dependent)
What does the IND-517-02 rejection code mean?
The IND-517-02 rejection code means that a Social Security number (SSN) on your return's dependent list is already the primary SSN or spouse SSN on another tax return for the same year. In plain terms, the IRS sees the person you are claiming as a filer in their own right. The IRS explanation for business rule IND-517-02 treats this as a possible duplicate claim.
A dependent is allowed to file a return. A teenager with a summer job, or a college student with a W-2, often files to get withholding back. The conflict appears when that return is filed as if nobody else can claim the student, because it leaves the IRS with two returns that disagree about who the person belongs to.
Like every reject, it means your return was not filed. You can see how this code fits with the others in our IRS reject codes list.
IND-517-02 vs IND-507-01: how are they different?
Both codes stop a second use of the same SSN, but they look at different spots on the other return. IND-517-02 finds the dependent's number in the filer or spouse position. IND-507-01 finds it in someone else's dependent section.
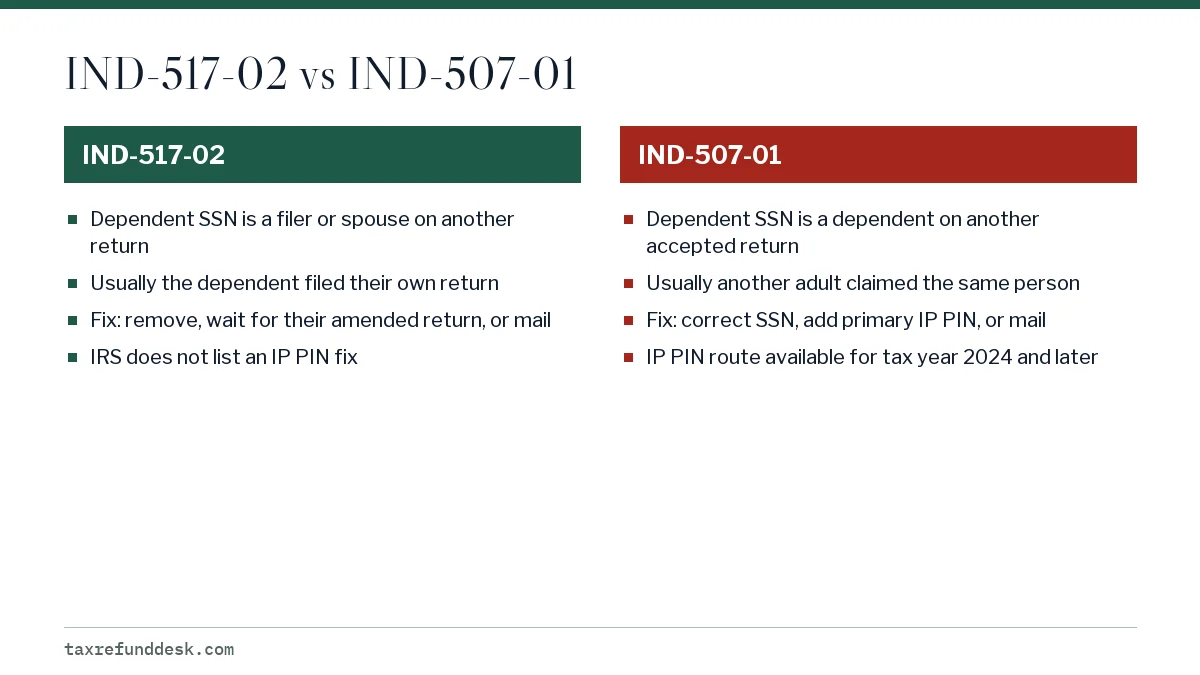
The difference changes who you talk to. With IND-517-02 the other return usually belongs to the dependent or your spouse, so the fix is often inside the family. With IND-507-01 it is another filer claiming the same dependent, which can be an ex-partner, a relative or a stranger.
IND 517 02: which dependent caused the reject?
Start with any dependent who had income last year, since they are the ones most likely to have filed. Then work through the rest of the list.
- Read the full rejection message. The explanation or the accompanying detail may include the SSN that failed; match it against your dependent list.
- List every dependent who had a job, tips, a scholarship with taxable parts, or investment income. Ask each whether they, or a parent's preparer, filed a return for them.
- Ask any adult dependent, such as a parent you support, whether they filed a return on their own.
- If you are married filing jointly, check whether anyone else, such as your spouse's parents, may have claimed your spouse. That is a separate cause the IRS names.
- Re-check every dependent SSN against the Social Security cards. A wrong digit can match a real filer who has nothing to do with you.
What are my options after an IRS reject code IND-517-02?
The IRS lists three solutions, and which one fits depends on what you learn from the family.
| What you found | What to do | Typical wait |
|---|---|---|
| The dependent filed and should not be your dependent | Remove them from your return and e-file again | None |
| The dependent filed but should be your dependent | Have them amend their return, then e-file yours after the amended return is accepted | Weeks to months; the IRS says to allow 8 to 12 weeks for a Form 1040-X |
| Someone else claimed your spouse as a dependent | Confirm with that person; if they should not have, mail your return | Paper processing time |
| All SSNs are correct and nobody should have filed | Print and mail your return and review IRS identity theft guidance | Paper processing time |
If the dependent needs to amend
The dependent files Form 1040-X to correct how they filed, in particular to show that someone else can claim them. Our Form 1040-X how-to walks through the form. Amended returns are processed in 8 to 12 weeks for most filers and up to 16 weeks for some, so waiting to e-file is only practical early in the season.
If you mail your return instead
Mailing lets you file now and let the IRS sort the conflict out afterward. If the deadline is close, use the timing rules in our e-file rejection grace period guide so the paper return still counts as on time.
A worked example: the student with a W-2
A 17-year-old earns wages at a summer job, with federal income tax withheld. In February she files her own return with free software to get the withholding back and does not indicate that her parents can claim her. The return is accepted.
In March her parents e-file a joint return listing her as a dependent. It comes back with IND-517-02. The parents have two realistic choices: she files Form 1040-X to fix her return and they wait for it to be accepted, or they mail their return now with her included. Removing her would only make sense if she really does not qualify as their dependent.
Had she instead appeared as a dependent on a grandparent's return, the parents would have seen IND-507-01, and a different set of fixes would apply.
When IND-517-02 points to identity theft
If every SSN is right, the dependent says they did not file, and nobody claimed your spouse, someone may have filed a return using the dependent's number. The IRS advice is to mail your return and review its identity theft information.
Identity theft involving a dependent may lead to IRS letters asking for proof later. The IRS pages on dependent identity theft explain what records it accepts. If an IP PIN turns out to be needed for the dependent afterward, see reject code IND-996 for how a dependent's IP PIN is entered on your return.
Step by step
Find the dependent
Check which dependent filed their own return, starting with those who had income.
Confirm the SSNs
Compare each dependent SSN with the Social Security card.
Pick the IRS fix
Remove a non-qualifying dependent, wait for the dependent's amended return, or mail your return.
Watch the deadline
Use the e-file grace period rules if the rejection is near the due date.
Common questions
Can I just remove the dependent to get my return accepted?
Only if they truly do not qualify as your dependent. Removing a qualifying dependent can mean giving up credits tied to them, and adding them back later means amending and facing the same conflict.
My child filed their own return. Do they have to amend?
If they should be your dependent and their return did not reflect that, the IRS fix for IND-517-02 is to wait until their amended return is accepted before you e-file. The other choice is to mail your own return.
Does IND-517-02 mean someone stole my child's identity?
Not usually. The common cause is a dependent who filed their own return. Identity theft is a possibility only when every SSN is correct and nobody in the family filed or claimed the person.
Why did my joint return get IND-517-02 for my spouse?
The IRS lists this as one cause: your spouse may be claimed as a dependent on someone else's return. Check with anyone who might have claimed your spouse; if they should not have, mail your return.
Will an IP PIN fix IND-517-02?
The IRS does not list an IP PIN as a fix for IND-517-02. Its options are removing the dependent, waiting for the dependent's amended return, or filing on paper.
Sources
- Business rule IND-517-02 irs.gov
- Business rule IND-507-01 irs.gov
- Where's My Amended Return irs.gov
- Identity theft: dependents irs.gov
We check figures against these official pages. Rules change; confirm anything that affects a deadline or payment with the agency before you act.
Tell us what happened
Describe your situation and our editors will use it to improve this guide. If you leave your email, we may reply with a pointer to the right page or official contact. We never share your details.